Capital One Auto Loan Pre-Approval Exposed: What Dealers Hide About Your Rate
 By Alexander Ross
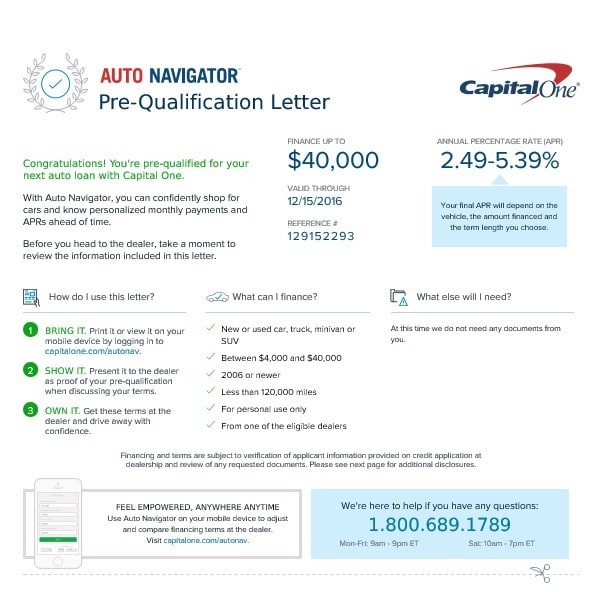
Capital One maintains broad vehicle financing requirements, catering to prime, near-prime, and subprime buyers. Unlike traditional credit unions that maintain strict underwriting cutoffs, Capital One works with buyers across diverse credit score thresholds. The cost of that flexibility varies dramatically by tier, and dealer markups punish lower-tier buyers far more severely.
| Credit Score Tier | Capital One Base Buy Rate | Allowed Dealer Markup | 5-Year Cost Impact on $35,000 Loan |
|---|---|---|---|
| Super Prime (781, 850) | 5.49%, 6.89% | Up to 1.00% | +$980 in added interest |
| Prime (661, 780) | 7.20%, 9.15% | Up to 1.50% | +$1,520 in added interest |
| Non-Prime (601, 660) | 10.45%, 13.80% | Up to 2.00% | +$2,110 in added interest |
| Subprime (501, 600) | 14.50%, 18.90% | Up to 2.50% | +$2,790 in added interest |
Borrowers in the lower tiers face significant compounding penalties when a dealer tacks on a markup. A buyer with a 590 credit score who accepts a 2.5% dealer markup on top of a 15% base rate pays nearly $3,000 extra on a standard vehicle purchase. That is pure dealer margin, detached from the vehicle's actual market value.
Alexander Ross has covered the video game industry for a decade, writing deep dives on game design, esports tournaments, VR developments, and gaming culture.
