The 2026 Loyalty Shift: How Bilt, Amex, and Chase Upended Points Redemption Rules
 By David Miller
Holding large quantities of points indefinitely exposes your portfolio to unchecked program devaluation. Points earn no interest, carry zero FDIC insurance, and can be repriced overnight at the sole discretion of the issuing bank. An optimal cash-out strategy does not mean hoarding rewards for a fantasy trip a decade away; it means setting an uncompromising value floor.
Before hitting the confirmation button on any redemption, apply this three-tier decision filter:
First, determine if the alternative cash cost of the booking justifies the point burn. If a flight costs $300 or 30,000 points, your yield is exactly 1.0 cent per point. Pay cash instead, earn points on the purchase, and save the balance for awards priced above 1.5 cents per point.
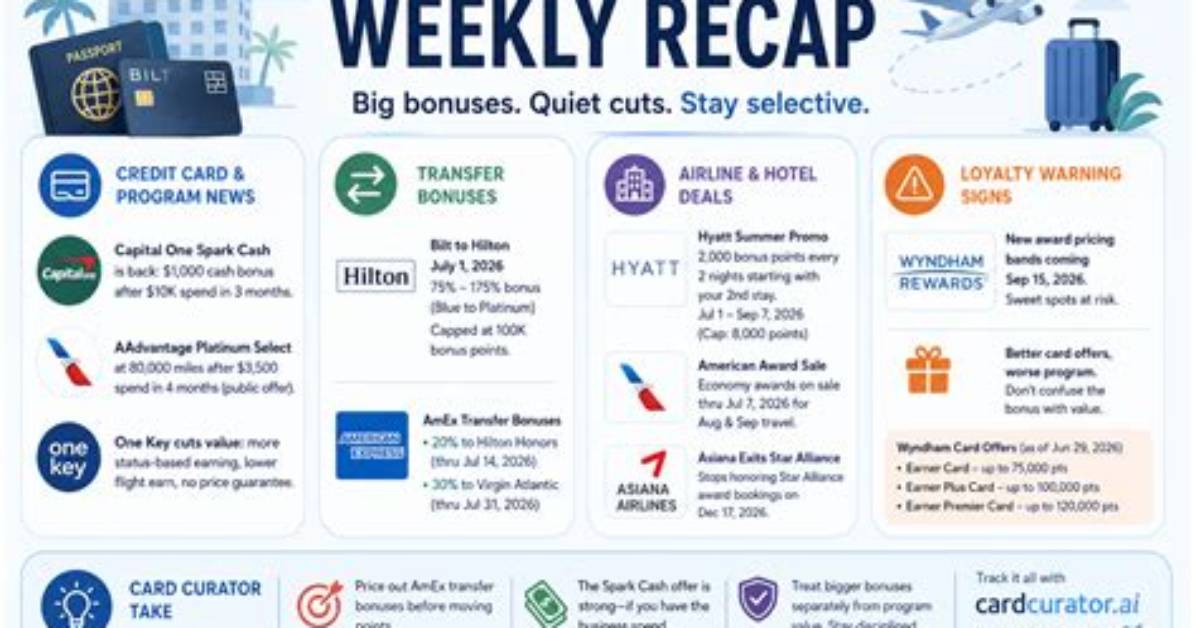
Second, monitor transfer partner bonuses before liquidating into travel portals. A 20% partner boost instantly decreases the absolute points required for the same route, beating portal pricing nine times out of ten.
Third, if your lifestyle shifts away from international or long-haul travel, stop collecting transferable currencies altogether. Pivot immediately to a dedicated, fee-free cash-back structure yielding 2% to 5% direct returns into a high-yield savings account. Liquidating premium travel points into retail gift cards to salvage value is an admission that you are carrying the wrong financial card products.
David Miller brings 15 years of experience in global economics, personal finance strategy, and market dynamics. He specializes in turning complex economic trends into actionable insights for everyday readers.
