Is the Tractor Supply Card Actually Worth It? the Truth Behind the Upgraded Neighbor’s Club Perks
 By James H. Sterling
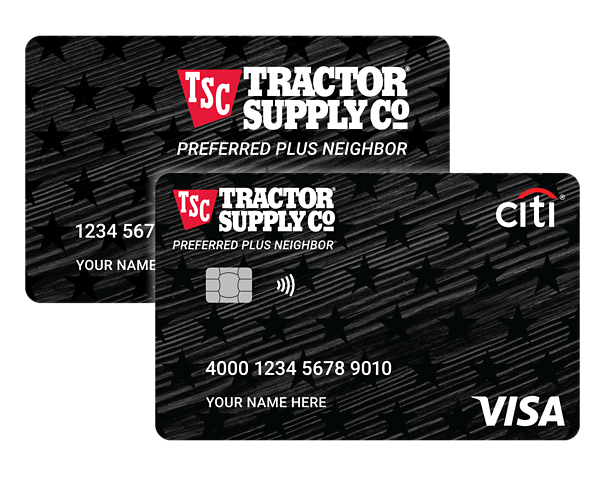
Behind the red-and-white TSC branding, this product operates as a standard Citibank retail card. Citi enforces rigid lending rules and maintains retail-tier interest charges that make carrying a monthly balance punishing. While the account features zero annual fee terms, the standard variable purchase APR frequently sits at 31.99% or higher, floating with the Federal Prime Rate.
Carrying a balance on everyday items completely wipes out the value of the 5% cash-back rate within two billing cycles. A $500 balance carried for three months generates more than $40 in interest charges, far outstripping the original $25 reward certificate. The product only functions effectively when treated as a charge card that is paid in full each month, or used exclusively for structured promotional payments.
| Product Feature | Standard Store Card | Visa Co-Branded Version |
|---|---|---|
| In-Store Earnings | 5 points per $1 (5% back) | 5 points per $1 (5% back) |
| Gas & Grocery Earnings | Not accepted outside TSC | 3% at gas stations, 1% elsewhere |
| Promotional Financing | 6 to 48 months (tier-dependent) | 6 to 48 months (in-store only) |
| Annual Fee | $0 | $0 |
| Approval Score Estimate | 640, 670 credit score | 680, 720+ credit score |
Applicants do not choose between the two versions at checkout. Citibank evaluates incoming applications based on credit history, debt-to-income metrics, and recent inquiries. Candidates with scores north of 680 to 700 are considered for the Tractor Supply Visa credit card, which can be swiped at gas stations, grocery stores, and general merchants worldwide. Borrowers sitting near the 640 to 660 baseline are typically approved for the closed-loop store card, which operates only at physical Tractor Supply locations and online at tractorsupply.com.
James Sterling reports on renewable energy developments, climate policy, ecological conservation, and green tech innovations around the globe.
